A court in Calgary just handed down a ruling that every business owner should pay attention to: the president of a respected, 50 year old Alberta company has been found personally liable for $35 million. Not the corporation. Him.
If you’ve spent decades building a business under the assumption that incorporating it drew a clean legal line between “the company’s problems” and “my family’s problems,” the Sunterra case is worth reading closely. It’s a reminder that the line most owners believe is automatic is often thinner and more conditional than they think.
Who Sunterra Was
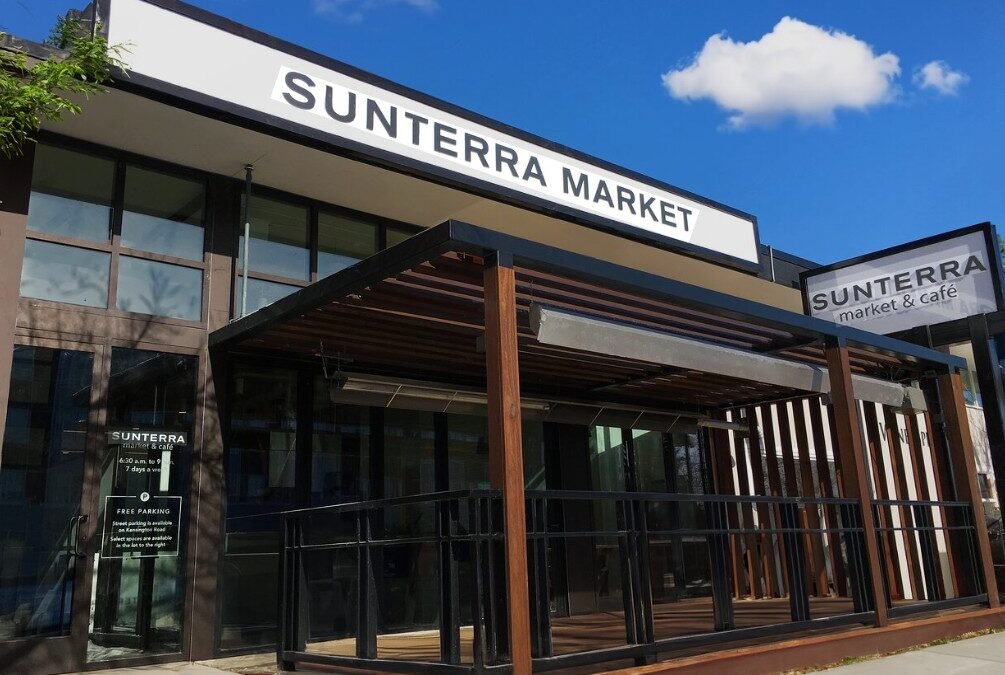
This isn’t a story about a fly by night operator or a startup that overreached. Sunterra got its start in hog breeding back in 1970 and, over five decades, grew into a vertically integrated agri food operation spanning hog farming, meat processing, and retail most visibly through its premium Sunterra Market grocery stores across Alberta.
That’s what sets this story apart from the usual cautionary tale, Sunterra didn’t fail because it was poorly run or undercapitalized, it failed to protect the one thing that should never have been on the table: the family’s personal position.
What Happened
The trouble originated on the U.S. side of the business. Three Sunterra owned hog finishing subsidiaries had pledged their pig inventory as collateral against loans from a U.S. agricultural lender, Compeer Financial. According to the lender’s claims, the companies’ account activity didn’t add up, cheques were allegedly being written and covered by other accounts that also lacked sufficient funds, a pattern known as cheque kiting. Compeer alleged it was owed more than $35 million against collateral worth roughly $19 million.
As the dispute unfolded, several Sunterra entities in Canada, including Sunterra Farms, Sunterra Food Corporation, Sunterra Quality Food Markets, Sunwold Farms, and Trochu Meat Processors filed for protection under Canada’s Bankruptcy and Insolvency Act, beginning a formal restructuring under court supervision. On the U.S. side, the hog subsidiaries at the center of the dispute were ultimately sold off to Tyson Foods a distressed sale, made on someone else’s timeline and someone else’s terms, not the ones Sunterra would have chosen for itself.
Then an Alberta court issued its ruling and found that Sunterra had engaged in cheque kiting on what the judge described as an “astonishing scale” and held the company liable to Compeer Financial for approximately $35 million.
What Happened Next
Here’s the detail that matters most for you … even if you’ve never kited a cheque in your life: the court didn’t stop at the corporate entity, it held Sunterra’s president personally responsible for the debt.
That single finding collapses the wall that most business owners assume protects them. Incorporation is not a force field. It’s a structure which have limits, gaps, and exceptions. Things like personal guarantees signed years ago and forgotten, blended personal and corporate assets that were never cleanly separated because nobody thought they needed to be, until suddenly they did.
You don’t need to be running a cheque kiting scheme for this lesson to apply to you. You need only have a business structure that was set up once, maybe years ago, maybe by an advisor who’s no longer in the picture and never revisited as the business, the debts, and the risks around it grew.
Why This Happens to Good Businesses, Not Just Bad Ones
The uncomfortable truth is that most owners have never actually stress tested the wall between their business and their personal wealth. A few of the quiet ways that wall gets thinner over time:
- Personal guarantees on loans, leases, or supplier agreements, signed in growth mode and never revisited
- Blended assets: personal and corporate finances that overlap in ways that blur legal separation
- Static corporate structures that were appropriate at $2 million in revenue but were never rebuilt for a business now doing $10 million or $20 million
- No independent personal financial plan where the owner’s retirement, savings, and family security are still, functionally, tied to the fate of the business
None of these require fraud to become a problem. They just require a lawsuit, a lender dispute, or a bad year that forces the question nobody had asked yet.
Build the Wall Before You Need It
The real takeaway from Sunterra isn’t about hog farms or cheque kiting. It’s about timing. The owners who avoid becoming a cautionary tale are the ones who reviewed their structure before a crisis forced the question, not after.
A few questions worth sitting with, regardless of how well your business is doing right now:
- If my business were sued tomorrow, do I actually know what’s protected or does it just feel protected?
- Have I personally guaranteed anything over the years that I’ve since forgotten about?
- Is my retirement plan genuinely independent of the business, or does it still rise and fall with the company’s fortunes?
- When was the last time my corporate structure was reviewed against where the business is today, not where it was when the structure was first built?
Sunterra spent fifty years building something real. The lesson isn’t that success is fragile, it’s that the protection around success needs just as much attention as the growth itself. The businesses that last are the ones where the owner’s personal future was never left resting on the company’s ability to avoid a worst case day.